The month ended. Sales were excellent, and the P&L shows a profit, and there is nothing suspiciously incorrect.
You should then check the restaurant’s bank account.
The number is not exactly what you’d hoped for.
This disconnect can be frustrating for restaurant owners since they believe that profit and cash available should speak the same truth. Both of them don’t match with each other. The P&L is a measurement of financial performance, whereas the bank account is a reflection of when money moves into and out.
Understanding the difference can alter how a business owner is looking at the restaurant’s financials.
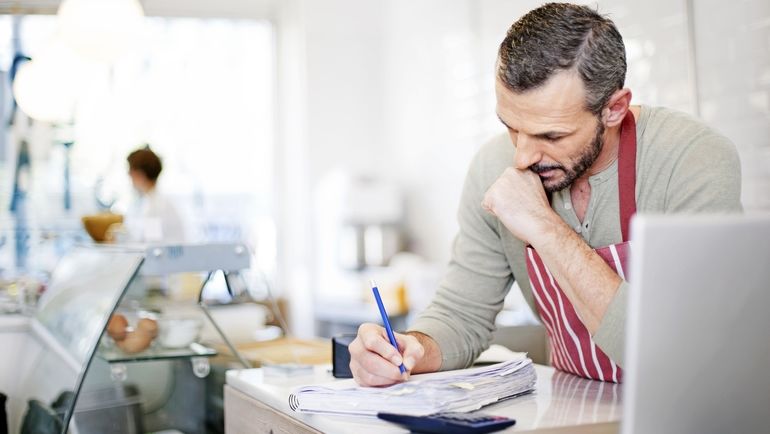
Imagine what could happen during an normal week. Customers pay for meals. Employees have to be paid. You will receive invoices with meals and beverages delivered. Rent is close to being paid. Deposits made with credit cards are subject to their own timetable. The tax on sales is an obligation.
Already, the next week’s purchases have begun.
If you focus only on the amount of revenue or profits, you’ll not be able to see a lot of the activity.
The key to the answer may lie in the prime cost
If restaurant profits begin to decrease, costs of food, beverages and labor expenses should be taken into consideration.
Cost of goods sold combined with labor is the prime cost. The bookkeeping chef’s guideline places the cost of goods sold at 60%-65 percent of the revenue for many restaurants, focusing on regular monitoring instead of waiting until the final day of the month.
Effective prime cost management is not about focusing on one particular percentage, and more about noticing movement quickly.
Let’s say that a restaurant typically performs within its targets however this week’s performance rises. Perhaps overtime was added. Perhaps beverage costs were steady, but food costs increased. The manager can review menus or waste, portion sizes along with vendor invoices and buying if the percentage of food is greater.
The percentage is the key. It is in the activity in the restaurant.
Weekly reports allow for this conversation to take place while everyone is still aware of what’s transpired.
The details are more difficult for you to remember just a few days later.
The Vendor’s Bills are Received
The restaurant pays in the future for the ingredients it buys. This is due to the fact that analyzing profits alone will not solve all cash problems.
Vendor invoices need to be accepted and tracked. In a business that has numerous suppliers, doing that by hand can be an administrative burden.
Automating the process of paying bills can assist in coordinating this process through reducing the repetition of bills and payments. The account owner will have an accurate picture of payments that haven’t been deposited into their bank accounts through the bookkeeping software that is connected to.
It’s helpful because, when viewed as a whole, a restaurant s bank balance could appear to be more healthy than its actual financial position.
It could be that there is $80,000 in the bank account at present. This amount could mean something different if it is impacted by other factors like rent or payroll, vendors, and other obligations in the next few days.
That leads naturally to cash flow forecasting.
What will happen with our cash after we’ve gotten the cash we’ve been expecting and have met our obligations?
It is important to know the difference between them when deciding whether this week is the ideal opportunity to replace equipment, purchase more products or save liquid funds.
It is possible that you weren’t eligible for all the money you thought.
The sales tax example is a great one.
Restaurants take money from their customers, which they have to be able to manage according to the tax requirements. When these dollars are mentally grouped together with operating cash, they can provide a false perception of the amount available for spending.
The consistent recording system allows restaurants comply with sales tax laws, while providing a realistic picture of their financial situation.
Accounting for restaurants is more efficient when the financial obligations of each restaurant do not have to be separated.
Prime cost affects margin. COGS (cost of goods sold) and future payments are impacted due to purchases made by vendors. Cash and labor percentage are affected by the payroll. Sales tax impacts the availability of cash. P&Ls keep track of financial performance and forecasting allows management to look ahead.
The pieces are joined.
Bookkeeping Chef helps bring these pieces together using restaurant-specific reports and system integrations. Outsourced bookkeeping services that are specifically tailored to your needs are an ideal option for operators who don’t have the time to manually reconcile financial information. They are able to handle the bulk of the accounting tasks without removing the owner from discussions about finances.
The last sentence is vital.
It’s not our goal for restaurant owners to stop checking their books because somebody else does. Owners need to be informed that will help them to understand what’s happening.
When the P&L reports that the restaurant earned money, but the bank account is feeling a little insecure, don’t believe that any of the numbers can be wrong.
Find out what transpired between you and your spouse.
That question can teach you more about your restaurant than any other number could be on its own.